
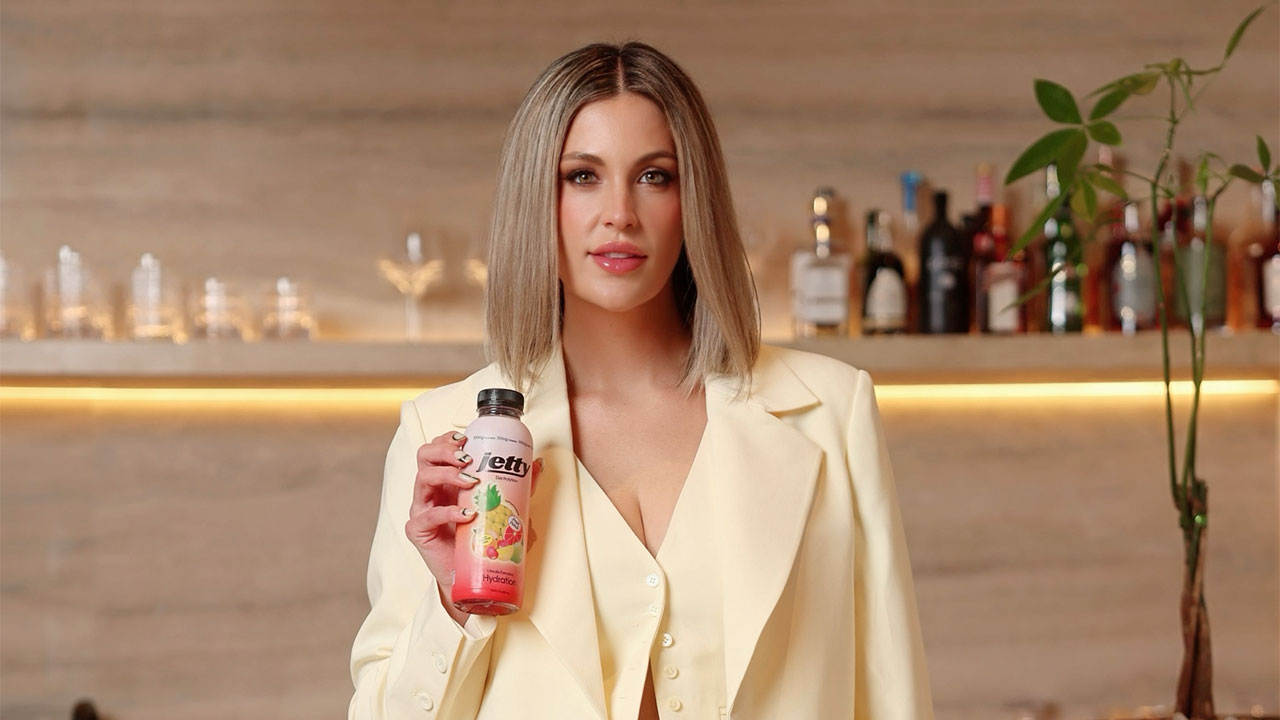
Jetty’s pitch: hydration for daily life, not just athletes
Allison and Stephen Ellsworth—best known for building Poppi and selling it to PepsiCo for nearly $2 billion—have quietly launched a new beverage brand called Jetty, positioning it as an electrolyte drink for everyday consumers rather than only for athletic performance. According to reporting on the founders’ launch, Jetty’s ready-to-drink formulas contain 100 mg sodium, 310 mg potassium, 100 mg magnesium, B vitamins, 6 grams of sugar and about 45 calories; the brand is debuting with five flavors available in bottles and powdered mixes nationwide through retailers like Whole Foods and online at Target and Amazon. (Coverage of the launch appeared in business media; see sources below.)
Why this matters: a big category and a familiar playbook
The founders are entering what they call a roughly $13 billion sports and performance drink category that, while historically marketed to athletes, is already widely purchased for everyday hydration. Beverage veterans point out that a large share of sports-drink consumption occurs outside workouts, creating an opening for brands that reframe hydration as part of daily routines for commuters, parents and office workers.
Playbook: digital-first branding, influencer reach and product formulation
Jetty’s strategy mirrors the digital-first approach that helped grow Poppi: strong social channels, influencer and creator engagement, and a focus on packaging and flavor that resonates on platforms like TikTok. Allison Ellsworth is leading branding and marketing while Stephen Ellsworth serves as CEO; the couple has invested seed capital into the business and is emphasizing lower sodium and a more everyday-appropriate electrolyte blend as a differentiator.
Market dynamics and practical hurdles
- Distribution and shelf space: Competing with legacy incumbents such as PepsiCo’s Gatorade and Coca-Cola’s Powerade requires strong retail slots and scale. New brands often find initial traction online or in specialty channels before expanding into mass retail.
- Repeat purchase economics: Attracting trial via marketing is one thing; building habitual consumption and favorable unit economics is another. Repeat purchases require a compelling price-quality-fit and reliable availability.
- Differentiation: Flavor, formulation (e.g., lower sodium, added vitamins/prebiotics), and distinctive branding help new entrants stand out. Recent challengers like Liquid Death and Liquid I.V. show that inventive positioning can cut through, but not every brand reaches scale.
- Capital needs: Scaling manufacturing, distribution, promotions and trade promotions demands meaningful funding—often several rounds—to compete head-to-head with global beverage giants.
What to watch next
Key signals of Jetty’s momentum will include expansion into additional retail banners and club channels, velocity (sell-through) at initial retail partners, repeat purchase metrics reported by the company or observed by retail partners, and whether the brand pursues larger retail distribution deals or raises outside capital to scale. Given the Ellsworths’ prior exit with Poppi, investors and category watchers will also be monitoring whether Jetty can scale brand affinity as quickly as Poppi did.
Bottom line
The launch of Jetty is a textbook example of founders applying lessons from a previous successful exit: lean digital marketing, formulation that addresses a perceived consumer pain point, and strategic retail rollouts. But success in the crowded beverage aisle depends on more than a strong story—it requires durable retail presence, consistent taste and repeat purchasing. Jetty’s early differentiation (a lower-sodium everyday electrolyte) and the founders’ existing media savvy give it advantages, but long-term success will depend on execution against distribution and repeat-consumption hurdles.
Sources and further reading:
- Fox Business coverage of the Jetty launch and interviews with the Ellsworths (reporting on product formulation, distribution and quotes)
- PepsiCo newsroom (company information and background on acquisitions such as Poppi)
- BevNET (industry coverage and analysis of emerging beverage brands)
- Statista (market data and category sizing for sports and performance drinks)
- Liquid Death and Liquid I.V. (examples of challengers that grew via distinctive positioning and digital marketing)